Best Home Appraisal Options in Austin, TX
Need a solid home appraisal in Austin? Here’s a quick shortlist of the most reliable choices and who they serve best.
1. Wheeler Appraisal: a local residential appraisal firm
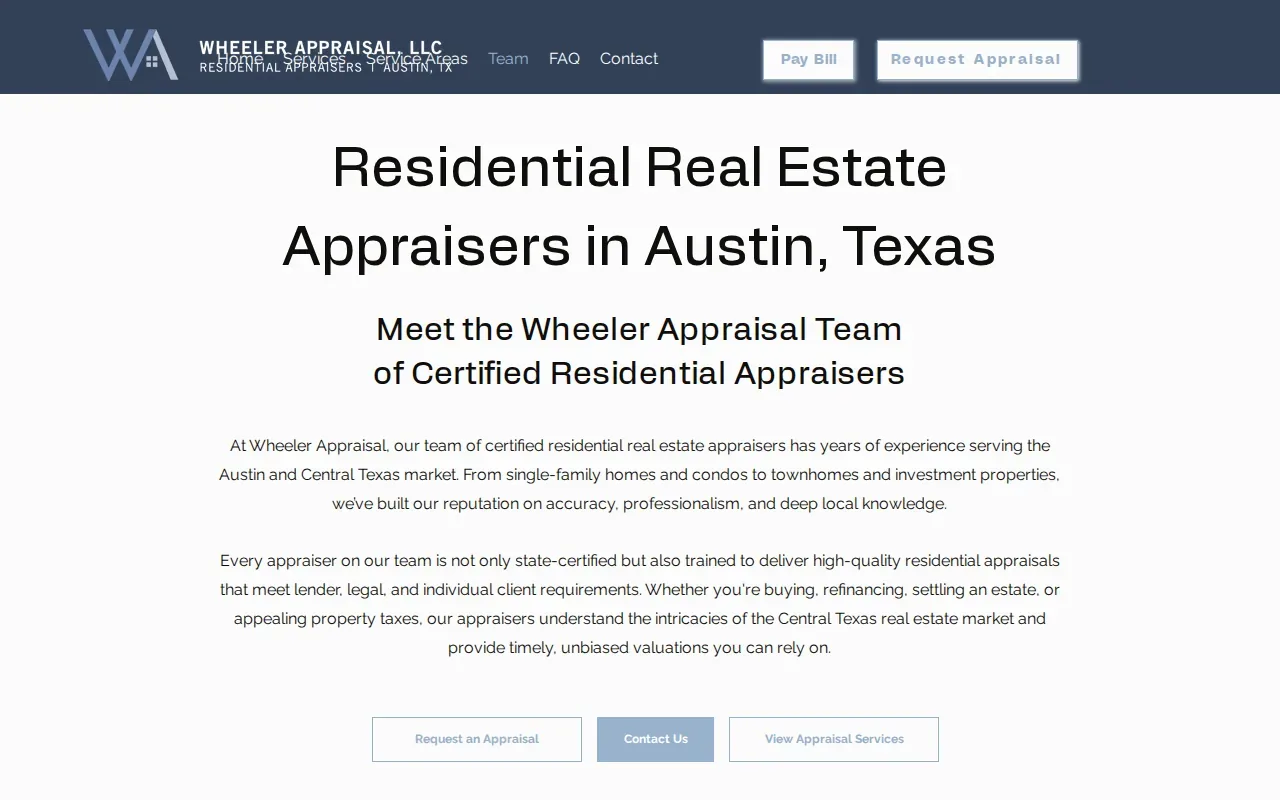
Wheeler Appraisal is a team of certified residential appraisers who focus on single‑family homes and small condos. They work out of central Austin and handle buyer, seller, and lender assignments. For more on appraisal reports, see How to read a home appraisal report.
The firm promises a PDF appraisal report within two business days for most residential orders. That fast turn‑time helps buyers stay on schedule when a lender needs the number to clear a loan. Wheeler also offers a separate insurance‑claim appraisal service, which can be useful if you’re dealing with a property dispute.
Because they specialize in residential work, they know the quirks of Austin neighborhoods, from Westlake to South Austin. Their local market knowledge lets them adjust comps for things like school district boundaries or proximity to the greenbelt.
One thing to note: ask for the current fee and any extra charges before you order, especially if you are on a tight budget.
2. Austin Home Appraisal Team: an independent Central Texas option
Austin Home Appraisal Team (AHAT) bills itself as an independent, locally owned firm that serves buyers, sellers, lenders, and investors alike.
What sets AHAT apart is the emphasis on a fully independent opinion of value. That independence can calm nerves when you’re negotiating a price or contesting a tax assessment.
The team offers a fast‑track service: most residential reports are delivered within three business days, and they keep you in the loop with daily email updates. If you need a rental‑income analysis for an investment property, AHAT can add that to the report for a modest extra fee.
A slight limitation: AHAT does not handle large‑scale commercial appraisals or complex multi‑unit properties. For those, you’d need a firm with a Certified General Appraiser license.
Because the firm is locally owned, they often have a personal touch, phone calls, on‑site walkthroughs, and quick answers to client questions.
3. Class Valuation: a lender‑channel option for mortgage appraisals
Class Valuation is one of the nation’s largest appraisal management companies (AMCs). Lenders use Class to order mortgage‑related appraisals, and the company routes the work to a network of vetted appraisers across the country, including Texas.
The AMC promises turn‑times that can shrink to two days for standard residential loans, thanks to a digital platform that lets appraisers upload data from the field in real time. That speed can be a real advantage when you’re racing to close a deal.
Class also provides a “collateral valuation” service for lenders who need extra risk analysis. Their platform includes tools for tracking order status, requesting revisions, and reviewing final PDFs.
A possible drawback: because Class acts as a middleman, you don’t work directly with the appraiser. If you prefer a face‑to‑face conversation about the report, a local firm like Wheeler or AHAT might feel more personal.
For borrowers, the key is that Class’s fees are bundled into the lender’s closing costs, so you often won’t see a separate line item. Still, ask your lender about any out‑of‑pocket charges before you sign.
How to Choose the Right Appraisal Provider
First, check that the appraiser holds a Texas Certified Residential Appraiser license. That ensures they’ve completed the required 200‑hour education and 1,500‑hour experience.
Next, think about timing. If you are ordering a private appraisal and need it fast, ask about turnaround before you book. For a mortgage, your lender orders the appraisal, so ask the lender how long its appraisal usually takes.
Finally, consider the level of personal service you want. Independent firms give you direct access to the appraiser; AMCs handle everything through a portal.
Frequently Asked Questions About Home Appraisals in Austin
What does a home appraisal actually measure?
A home appraisal estimates the fair market value of a property based on its condition, size, location, and recent comparable sales. Lenders use that number to decide how much they’ll loan.
How long does an appraisal take?
Turn‑around time varies. Most local firms deliver a report in two to five business days, while larger AMCs can sometimes do it in as fast as two days if the loan is standard.
Can I choose my own appraiser?
Not for a mortgage. Federal appraiser independence rules require the lender, or an appraisal management company it hires, to select the appraiser, and borrowers cannot pick or pressure them. For a private appraisal, such as before listing, for a property tax protest, or for an estate, you can hire any licensed appraiser you like.
Do appraisals include rental‑income analysis?
Only if you ask for it. Some firms, like Austin Home Appraisal Team, add a rental‑income section for investors. Mortgage‑only appraisals typically focus on market value.
What should I do if the appraisal comes in low?
Start by reviewing the report for errors. If you spot a mistake, you can request a reconsideration of value with supporting data, or negotiate a new price with the seller. For more detail on what to do when an appraisal comes in lower than your offer, consider the possible next steps and who may be responsible for the difference.
Are appraisal fees tax‑deductible?
Generally, appraisal fees paid by the buyer are part of closing costs and aren’t tax‑deductible. If you paid for an appraisal for another reason, ask a tax professional how it applies to your situation.
Choosing the right appraisal partner can keep your transaction on track and give you confidence in the price you’re paying. If you are ordering a private appraisal and want a local, hands‑on approach, a firm like Wheeler Appraisal or Austin Home Appraisal Team is a good place to start. If your lender orders the appraisal, it will choose through its own channel, which may be an AMC such as Class Valuation.
Over the years I have built working relationships with experienced professionals who consistently put clients first, and I am glad to share names. You are always free to choose any provider you wish.
Ready to move forward? Check the latest Austin market forecast and then give me a shout so we can line up the best appraisal for your situation.
Robbie English, REALTOR, Broker at Uncommon Realty
Categories
- All Blogs (1011)
- !!! (59)
- !x (621)
- Austin Real Estate (113)
- Bee Cave Real Estate (1)
- Building A Home (16)
- Buying A Home (156)
- Buying Land (1)
- Cedar Park Real Estate (59)
- Central Austin Real Estate (75)
- Down Payment Assistance Programs (1)
- Downsizing (4)
- Downtown Austin Real Estate (5)
- Dripping Springs Real Estate (62)
- East Austin Real Estate (3)
- Financing and Mortgage (24)
- first-time homebuying (110)
- Georgetown Real Estate (11)
- Hill Country Real Estate (1)
- HOA (3)
- Home Appraisals (14)
- Home For Rent (1)
- Home Inspections (14)
- Home Pricing (6)
- Home Staging (1)
- Home Values (12)
- Home Warranties (1)
- Homeownership (1)
- Homes For Rent (1)
- Homes For Sale (147)
- Hutto Real Estate (6)
- Insurance (1)
- Investing (6)
- Investment Properties (4)
- Lakeway Real Estate (33)
- Leander Real Estate (59)
- LGBT+ Real Estate (8)
- Luxury Homes For Sale (5)
- Luxury Real Estate (19)
- Market Conditions (17)
- Moving to Austin (2)
- Moving to Texas (4)
- Negotiations (3)
- Neighborhoods (8)
- Northwest Austin Real Estate (94)
- Off Market Listings (7)
- Pflugerville Real Estate (11)
- Private Listings (2)
- Property Management (42)
- Property Tax (5)
- Real Estate (18)
- Reddit Question Answered (80)
- redwrite (63)
- Relocation (2)
- Renting (6)
- Representation (38)
- Round Rock Real Estate (59)
- Selling Your Home (66)
- South Austin Real Estate (1)
- Westlake Real Estate (3)
Recent Posts